Retirement shouldn't feel like a guess.
You've spent decades earning and saving. Now comes the part nobody prepared you for: turning what you've built into income that lasts: predictably, tax-efficiently, and without lying awake doing bracket math. That transition, from earning to drawing, is exactly what this lane is about.
Does this sound familiar?
- You're within a few years of stopping work, or already there, and the plan is mostly "we'll see."
- You're not sure when to file for Social Security, and everyone you ask says something different.
- RMDs are coming, and you suspect they'll push you into a higher bracket.
- You're worried taxes will quietly eat years of your savings.
- You want the people you love protected no matter the order life happens in.
Every one of those is a solvable planning problem. The difference between a guess and a plan is that a plan is written down, runs on real numbers, and gets pressure-tested every year.
Start with the check
The Retirement Blind Spot Check
Seven quick questions that reveal what your retirement plan might be missing — and a clear next step either way. Two minutes, no login to see your score.
NewThe $50,000 Decision: 62, 67, or 70?
One decision. Permanent. Worth up to six figures. Make the call you'd make, then see what the math didn't ask you.
Try it nowThe Retirement Tax Leak Audit
Twelve questions to spot where taxes could quietly drain your retirement, and where to focus first. Five minutes, no login.
Try it nowThe Retirement Decision Matrix
Sort your retirement concerns into what to decide now, prepare next, monitor, or safely ignore.
Try it nowFinancial Calculators
Social Security timing, RMDs, inflation and retirement income, lump sum vs. payments, and more: ten quick calculators to run your own numbers.
Distribution planning is its own discipline
Saving money and drawing it down are different skills. The second one is where taxes, Social Security timing, Medicare premiums, and withdrawal order all interact.
It's Bob's specialty: he concentrates on tax, estate, and distribution strategies, and is one of only 200 advisors in the United States trained on the advanced retirement distribution research of Curtis Cloke. As fiduciaries, everything we recommend is legally required to be what's best for you.
Own a business? Selling it is often part of the retirement plan. See Owning a Business.
A holistic investment strategy
Four steps first: income needs two years ahead, protection against loss, estate and tax efficiency, then the rest of your portfolio. That rest goes to work in three buckets.
- Bonds and CashThe next 2 years of income
- 50/50Income Assets Used In Years 3 to 9
- Stocks and EquitiesLong-term growth
From a guess to a written plan
- A free first conversation. By virtual appointment, from wherever you are. Tell us where you stand and what worries you.
- A plan on your real numbers. Social Security timing, withdrawal order, RMDs and taxes, worked out together and written down.
- Income you can count on. A paycheck from what you’ve saved, sequenced to keep taxes low.
- Pressure-tested every year. We review the plan each year as tax rules, markets and your life change.
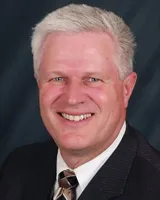
Bob Ward
Bob has held senior planning positions for over 40 years and leads Oaks as Chief Executive Officer and Financial Architect. And you won't only get to know Bob: Oaks is a two-advisor firm, and clients get to know both of us over time, not just whoever's focus matched their first question. Read his full bio.
Your plan. Your team. Your continuity.
One of the most common questions thoughtful clients ask is: "What happens to my plan in the future?"
Oaks is built as a firm, not a one-person practice. While Bob remains your primary advisor, Andy is already deeply involved in the planning philosophy, strategy, and long-term direction behind your plan, not a name you'd meet for the first time someday. Your relationship with this firm was never designed to depend on one person being available forever.
- A consistent planning philosophy
- A shared understanding of your goals
- A team approach designed for longevity
Our goal is simple: your financial strategy should outlast any one individual. Your plan is supported by a process, a team, and a long-term vision.
Read the guides
Am I Ready to Retire?
A rule of thumb for the money (income that covers about 70 to 80% of what you earn now), and the seven psychological factors that shape how well you enjoy retirement.
RetirementHow Should I Position My Savings for Retirement?
Building wealth is how you accumulate the assets. This is how to position them for retirement: four steps, then three buckets for the next two years of income, years 3 to 9, and long-term growth.
RetirementWhat If I Live to 100? Planning for a Long Retirement
Average life expectancy is the wrong number to plan around. Why women especially should plan for their mid-90s or beyond, and the five ways a plan makes money last as long as you do.
RetirementShould I Take Social Security at 62, 67 or 70?
What each Social Security filing age pays, who each one fits, why break-even tables mislead, and what decides your best age.
RetirementWhat Is a Required Minimum Distribution?
RMDs force taxable withdrawals from pre-tax retirement accounts starting at 73. How the amount is set, and how to shrink it by planning in your 60s.
RetirementHow Much Can I Safely Withdraw From My Savings Each Year?
The 4% rule is a starting point, not a promise. What it means, why the right number depends on you, and how the order you draw from your accounts changes your taxes.
RetirementWhat Is Sequence of Returns Risk?
Two retirees can earn the same average return and end up with very different savings. The difference is the order the good and bad years arrive, and it matters most right around retirement.
RetirementDoes It Matter Which Account Holds Which Investments?
Asset allocation is what you own. Asset location is which account holds it. The same investments can leave you with more after tax depending on where they sit.
Show 9 more guides Show fewer guides
How Does Inflation Affect Retirement Income?
A retirement can last 30 years or more, and prices rarely stay put. What a steady rate of inflation does to what your money buys, and what to check in your plan.
RetirementWhat Should an Annual Retirement Plan Review Cover?
A plan is only as good as its last check. A short yearly checklist: spending, investments, taxes, Social Security and Medicare, beneficiaries and what has changed in your life.
TaxesWhat Is a Roth Conversion, and When Is It Worth It?
A Roth conversion moves pre-tax IRA money into a Roth and pays the tax now. When it works, how it compares with leaving the money alone, and who each choice suits.
RetirementWhat Will Healthcare Cost Me in Retirement?
Healthcare is the largest expense most retirement plans underestimate, and long-term care is the one families avoid. What each costs, and how to plan early.
RetirementWhat Do Medicare Parts A, B, C and D Cover?
Part A covers hospital stays, Part B doctors and outpatient care, Part D prescriptions, and Part C (Medicare Advantage) bundles them privately. How they fit.
TaxesWhy Is My Tax Refund So Big (or So Small)?
Tax withholding is what your employer sends the IRS from each paycheck, set by your W-4. How to fix a big refund or a surprise bill by updating it once.
FiduciaryWhat Is a Fiduciary Financial Advisor?
A fiduciary must recommend what is best for you; a non-fiduciary only what is suitable. What each standard means, how they differ, and how to check which one your advisor works under.
RetirementHow Does a Reverse Mortgage Work?
How a reverse mortgage works, how it compares with downsizing, and the one question that decides which fits, and why timing matters more than the product itself.
RetirementCan Life Insurance Provide Retirement Income?
Why some people fund a permanent life insurance policy well beyond the death benefit, in their building years, to shrink a large balance just before RMDs start, and again once RMDs start.
Straight answers
At what age can I start Social Security?
Anywhere from 62 to 70. Filing before your full retirement age (67 for anyone born in 1960 or later) permanently reduces your monthly benefit; waiting past it grows the check about 8% for each year you wait, until 70.
Why does Social Security timing matter more for married couples?
Often different ages for each spouse. When one dies, the survivor keeps the larger check and loses the smaller one, so the higher earner's filing age sets the survivor's income for what could be decades, while the lower earner has more room to file earlier for cash flow.
What is a required minimum distribution?
The yearly amount the IRS makes you withdraw, and pay income tax on, from pre-tax accounts once you reach the trigger age: currently 73, moving to 75 for younger generations under current law. The amount is each account's balance divided by an IRS life-expectancy factor.
When is the best time to do a Roth conversion?
Often the stretch between retiring and starting Social Security and required withdrawals, when taxable income drops and the lowest brackets sit mostly unused. Converting in those years can move money out at 12% that would otherwise come out at 22% or higher.
Does Medicare pay for long-term care?
No. Medicare covers limited skilled nursing after a qualifying hospital stay, not the years of help with daily living most people picture when they think of a nursing home. That gap is the reason to plan.
Does tax withholding end in retirement?
No. IRA withdrawals, pensions, and even Social Security need their own withholding elections, and nobody sets them for you.
Is Oaks Financial Services a fiduciary?
Yes. We hold ourselves to the fiduciary standard on every recommendation, and our obligations are described in our Form ADV, which we are glad to walk through with you line by line.
Do you work with people outside Minnesota?
Yes. Every meeting is a virtual appointment, so we work with people anywhere in the United States, and the first conversation is free.
Start with one question
What's the one retirement thing that nags at you most? Tap it, get a straight answer, and see where it leads, no cost, no obligation, no pitch.
No office to walk into. Just meet us from home.